Business · NEWS EXPLAINER
Shriram Finance cuts FY27 growth outlook as shares hit an 11-month low
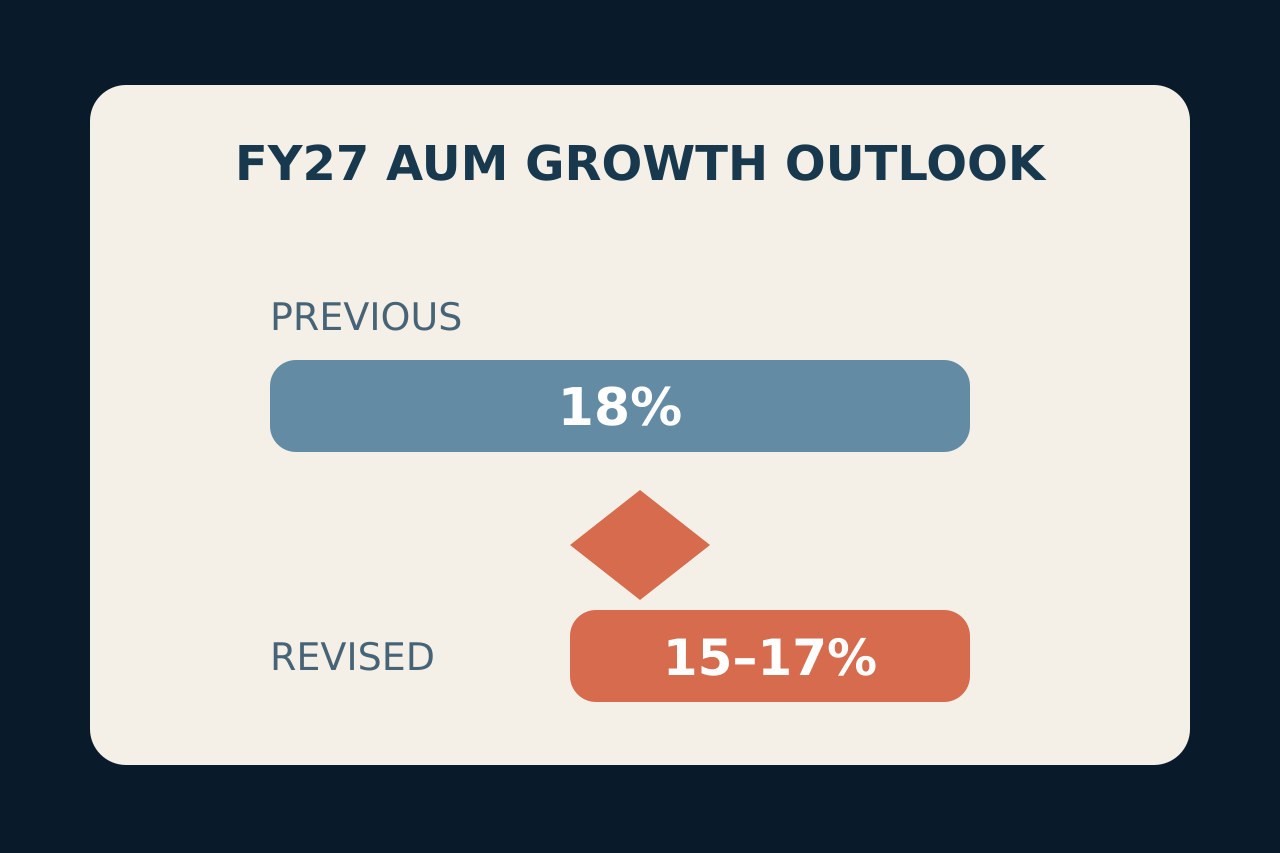
The lender lowered expected asset-under-management growth to 15–17% from 18% and warned that credit costs may stay elevated for one or two quarters.
Shriram Finance shares fell as much as 6.13% to 810.20 rupees on October 26, their lowest level in 11 months, after the lender lowered its FY27 growth outlook.
The company now expects assets under management to grow 15–17%, down from 18%. Quarterly profit rose, but higher impairment charges and borrower stress complicate the headline.
What changed in guidance
Shriram Finance reduced its FY27 asset-under-management growth expectation to 15–17% from 18%. Reuters reported that management pointed to a weak monsoon, geopolitical uncertainty and borrower stress. The change is a management forecast, not a completed annual result.
Why credit costs matter
The lender said credit costs could remain elevated for another one or two quarters. That matters because higher expected losses can absorb part of the benefit from loan growth and interest income, even when headline profit is rising.
Profit still rose
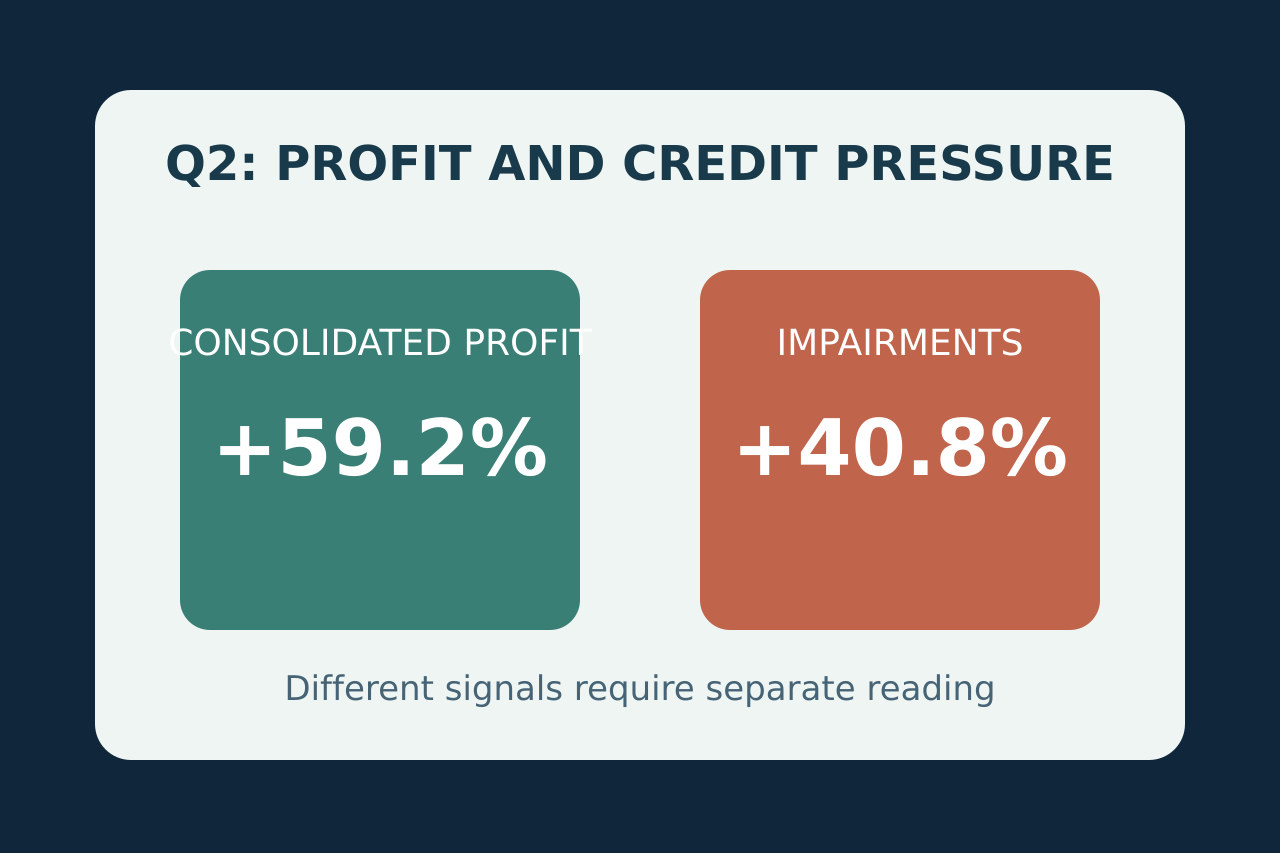
Reuters reported standalone quarterly profit of 36.77 billion rupees, above the 35.46 billion-rupee analyst average it cited. Financial Express reported consolidated net profit of 36.8381 billion rupees, up 59.2% from a year earlier. These measures are close but not interchangeable.
Income, funding and provisions
Financial Express reported consolidated total income of 138.0184 billion rupees, interest income of 133.8584 billion, finance costs of 49.6490 billion and impairment charges of 18.7740 billion. Impairments rose 40.8% year over year, adding context to management’s warning on credit costs.
What readers should not infer
The update establishes a lower growth range, elevated near-term credit costs and a sharp market reaction. It does not establish where the share price or full-year profit will finish. This is factual business reporting, not investment advice.