Business · NEWS EXPLAINER
Infosys shares fall after FY27 growth forecast is cut to 1–2%
The company kept its 20–22% margin outlook and reported strong AI and large-deal figures, but a weaker growth range and North America pressure drove a sharp early reaction.
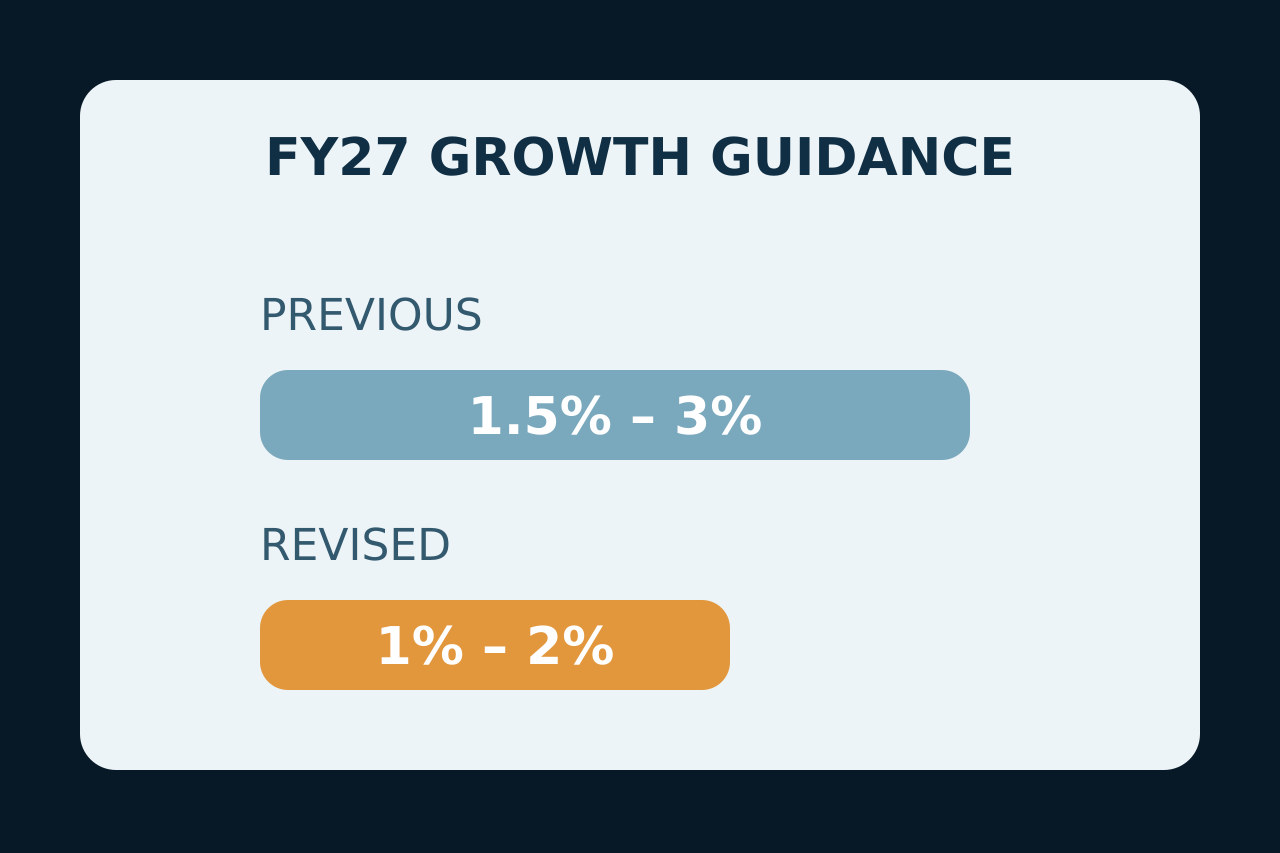
Infosys shares fell 2.7% in early Indian trading on October 26 after the IT-services company cut its fiscal 2027 constant-currency revenue growth forecast to 1–2% from 1.5–3%.
The revision does not mean revenue is shrinking. It means management now expects a smaller full-year increase, while holding its operating-margin forecast at 20–22%.
What changed
The previous 1.5–3% range allowed for a stronger upper-end year. The new 1–2% range cuts both the floor and ceiling. Reuters reported that most analysts had expected only the upper bound to fall to 2.5%, making the published revision more cautious than the consensus it cited.
Why the market reacted
Reuters reported weakness in the North America business and analyst concerns about pricing pressure, AI-linked productivity demands, softer technology spending and contract ramp-downs. The shares initially fell faster than the broader Nifty IT and Nifty 50 indexes, although the gap narrowed during early trading.
The quarter was not uniformly weak
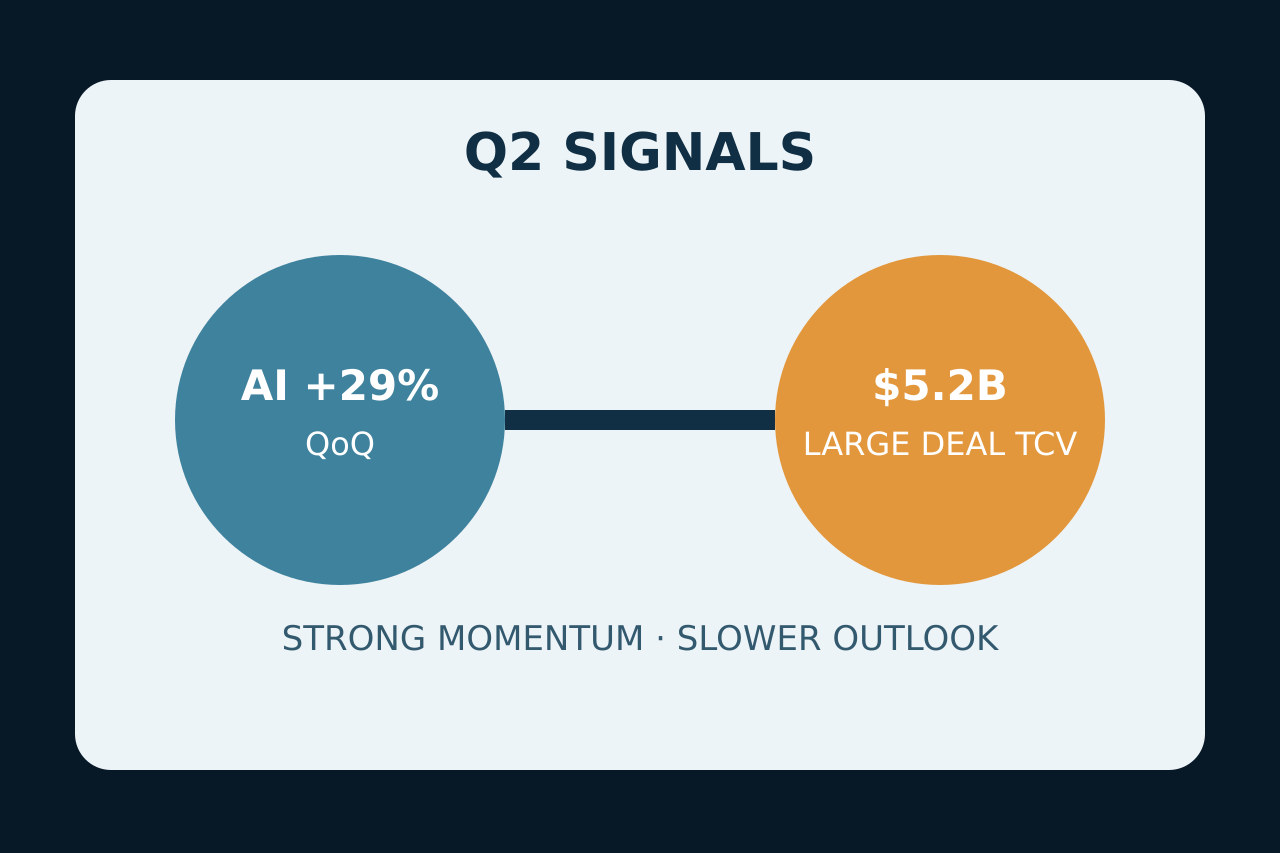
Infosys reported $5.145 billion of Q2 revenue, 21% operating margin and $5.2 billion of large-deal TCV. AI revenue reached 10.5% of company revenue and grew 29% from the prior quarter. Those figures show deal and AI momentum even as the full-year growth range was reduced.
Growth and margin are different questions
The company left its FY27 operating-margin range at 20–22%. A lower revenue-growth forecast therefore does not automatically imply the same reduction in the margin outlook. Delivery mix, pricing, cost controls and the timing of client work can move the two measures differently.
What the numbers establish—and what they do not
The update establishes a narrower management forecast and a negative early share reaction. It does not guarantee where revenue, margins or the share price will finish. The company labels its outlook forward-looking, and this report is factual business coverage rather than investment advice.