Business · NEWS EXPLAINER
DSV profit beats forecasts as Schenker gains offset Road weakness
Adjusted operating profit rose 19.5%, but Road earnings fell 35.1% and some integration synergies moved into 2027.
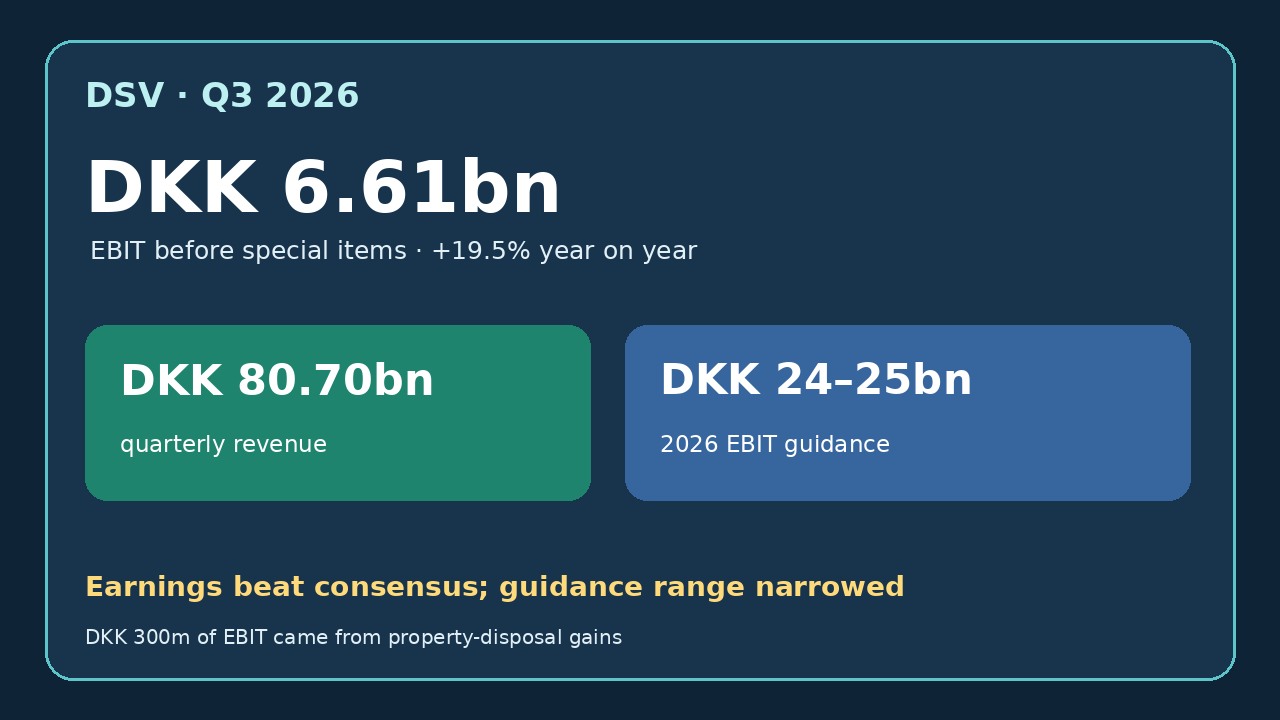
DSV reported third-quarter adjusted operating profit of DKK 6.606 billion, above consensus, as Air & Sea and Contract Logistics benefited from Schenker integration synergies.
Road remained the weak spot, while the company narrowed—not raised—its full-year earnings range and launched a DKK 1.5 billion buyback.
Profit growth beat expectations
DSV reported third-quarter EBIT before special items of DKK 6.606 billion, up 19.5% from a year earlier and 4.0% above the DKK 6.354 billion company consensus. The figure included DKK 300 million of gains from property disposals, so the headline and the underlying operating story should be read together.
The Schenker integration produced uneven results
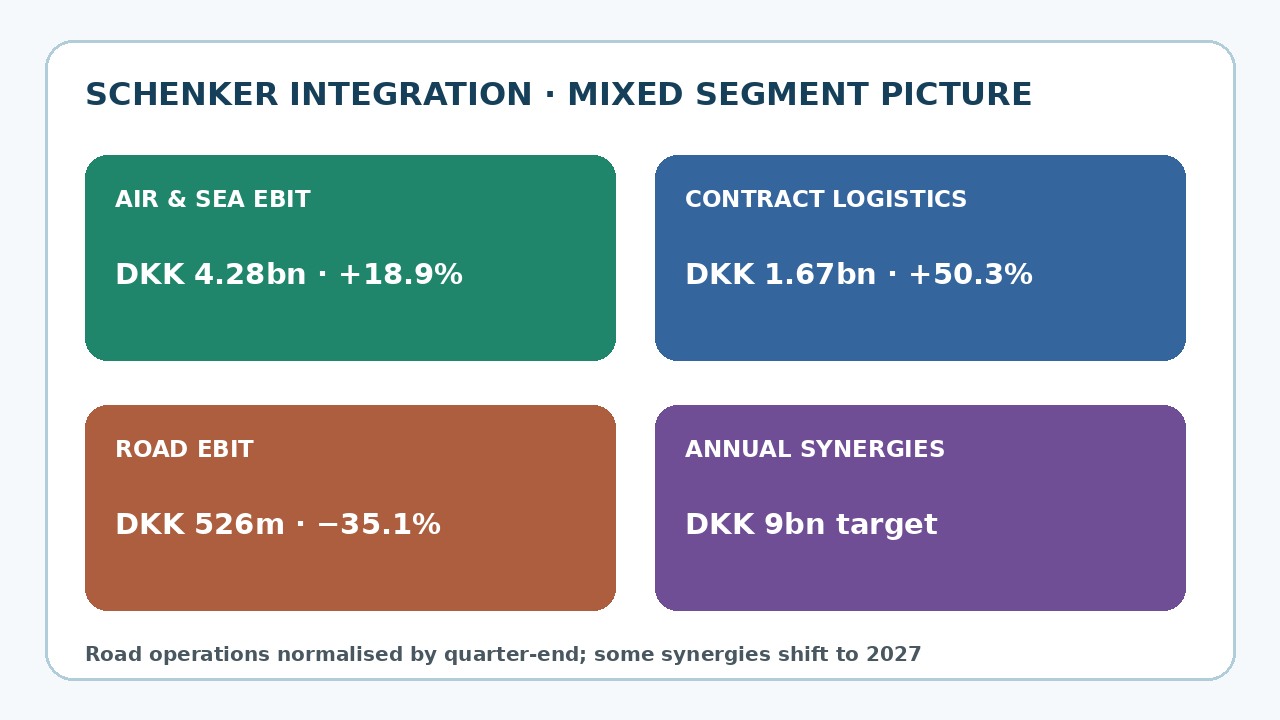
Air & Sea EBIT rose 18.9% to DKK 4.278 billion and Contract Logistics EBIT rose 50.3% to DKK 1.673 billion. Road EBIT fell 35.1% to DKK 526 million as reduced service reliability hurt volumes and productivity, although operations normalised by quarter-end.
Guidance narrowed without lifting the midpoint
DSV narrowed 2026 EBIT-before-special-items guidance to DKK 24–25 billion from DKK 23.5–25.5 billion. The midpoint stayed at DKK 24.5 billion. Expected 2026 integration special items fell to about DKK 5.5 billion from DKK 6.5 billion because some costs and synergies shifted into 2027.
Cash flow supported deleveraging and a buyback
Adjusted free cash flow reached DKK 6.439 billion and the gearing ratio fell to 2.5 times. DSV launched a DKK 1.5 billion share buyback running from October 21, 2026 to February 1, 2027, its first since the Schenker acquisition.